Africa Must Invest in Gas to Close Energy Gap
By Dr. Philip Mshelbila
It is a great pleasure to attend African Energy Week for the first time as Secretary General of the Gas Exporting Countries Forum (GECF). I sincerely thank our host, the African Energy Chamber, for the invitation and warm hospitality.
The theme of this year’s African Energy Week, “Invest in African Energies: Affordable and Abundant Energy Additions,” sets a very clear priority for us: turn Africa’s resources into energy that its people can access, afford and depend upon.
The whole world needs more energy, and it needs energy that is reliable and cleaner.
Nowhere is the need greater than in Africa. Today, nearly one in five people on Earth lives in Africa, yet the continent accounts for less than six per cent of global energy use. By 2050, Africa will add another billion people and become home to roughly one in four people on the planet.
Yet, based on current trends, Africa will still consume less than 10 per cent of the world’s energy.
So, we have a growing share of humanity with a persistently unequal share of energy. This is the gap we must close. It places a profound constraint on development.
Even as Africa’s energy demand grows by nearly 80 per cent by 2050, energy consumption per person will remain far below the global average. Meeting basic human development needs therefore requires a much greater expansion of affordable energy supply. It requires investment that delivers tangible improvements in living standards.
The recent geopolitical crisis has brought this challenge into sharper focus. It is a structural stress test, exposing vulnerabilities that affect energy security, food security and economic resilience.
At the GECF, we define energy security as the sustained ability of the entire energy system to deliver affordable and reliable energy under normal conditions, during crises and as future needs evolve.
In other words, energy security must be dynamic. It is not static, particularly in a fast-changing world. But it starts with access to affordable energy.
The continent of Africa holds more than 15 trillion cubic metres of natural gas, representing more than eight per cent of global reserves.
There was considerable discussion on gas in the previous session, and I was very pleased to hear that.
These resources offer substantial opportunities to meet domestic and regional needs, anchor export-oriented industries and supply international gas markets.
Natural gas is therefore more than a fuel and certainly more than a foreign exchange earner for our countries.
For Africa, gas is not merely a transition fuel. It is a transformation fuel. It is a strategic enabler of development and resilience.
It provides baseload, flexible and dispatchable electricity that stabilises grids and complements renewables. It can displace costly imported oil products and carbon-intensive coal while supporting industrial growth.
It supplies feedstock for fertilisers that strengthen food security, as well as petrochemical products that are essential to life as we know it today.
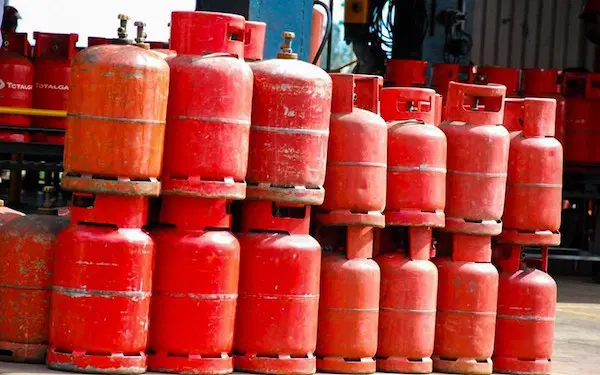
Gas can also be processed into LPG for cleaner cooking.
Therefore, when developed strategically, natural gas can strengthen domestic and regional energy value chains, create jobs and improve Africa’s capacity to manage volatility and external shocks.
But resources become development only when investment connects them to people.
Ladies and gentlemen, allow me to highlight five priorities for natural gas in Africa.
First, we have to increase upstream production.
Undeveloped reserves mean nothing until they are monetised.
We can boast all we like about how many trillion cubic feet of gas we have in the ground, but it means absolutely nothing until we can translate those resources into investment and monetise them.
Sustained investment is needed not only to address natural decline but also to develop new supplies.
Let me highlight one point: 80 per cent of annual capital expenditure in the upstream industry since 2019 has gone simply into addressing natural decline. Only 20 per cent has gone into creating and developing new additions.
Significant investment is therefore needed to meet the expected 31 per cent growth in natural gas demand by 2055.
Another point to note is that we estimate that 86 per cent of the gas needed by 2055 will have to come from new, currently undeveloped fields.
This represents a huge capital requirement.
Second, we must build out infrastructure and interconnectivity at domestic and regional levels to improve access to both molecules and electrons across the continent.
In addition to major projects such as the Trans-Saharan Gas Pipeline, the African Atlantic Gas Pipeline and pipelines in the Southern African region, many more projects will be needed to create a pan-African natural gas network, as well as a pan-African power pool.
Third, domestic and regional value addition.
While international pipeline and LNG exports are important for generating much-needed foreign exchange revenue, the true economic value and multiplier effect of natural gas come when it is processed locally into value-added products such as fertiliser, petrochemicals, plastics, fabrics and much more.
This must be a priority for our resource holders.
Fourth, financing.
Africa needs innovative financing options that cater to its unique needs.
Understanding the value-chain economics of all investment streams and establishing balanced risk-reward sharing between resource holders, investors and operators will help unlock currently inaccessible financing.
Key to this critical development objective is resolving domestic gas pricing.
I repeat: we have to resolve domestic gas pricing.
The economics of the domestic gas value chain in most of our countries do not work. That is why most investors would rather focus on exports.
This has to be resolved because, until we do so, it will be difficult for investors to put money into gas projects that serve the domestic and even regional markets.
Fifth, cooperation and partnership.
Much closer cross-border cooperation is needed to realise these ambitions.
Aligned regulatory, legal and fiscal frameworks are required to support domestic and regional development by lowering barriers to investment in regional projects and infrastructure.
These priorities give practical expression to the ambitions of Agenda 2063, the African Continental Free Trade Area and Mission 300, all of which seek greater access, regional integration and inclusive prosperity.
Ladies and gentlemen, the GECF is proud to support this vision.
Nine of our 20 member and observer countries are African — nearly half of the GECF family.
Therefore, Africa’s priorities are our priorities.
Africa’s energy future will be built by Africans, with partners who share that vision.
Africa has the resources. Its people have the ambition. Our collective responsibility is to connect the two through investment, financing, infrastructure and cooperation.
*** Being the full text of Dr. Philip Mshelbila, the fifth Secretary General of the Gas Exporting Countries Forum (GECF) at the just concluded African Energy Week 2026